Why Europe’s New Charging Infrastructure Regulations Will Reshape Distributor Sourcing in 2026
Home / Blog / Industry News / Why Europe’s New Charging Infrastructure Regulations Will Reshape Distributor Sourcing in 2026
13 Oct, 2026
AFIR 2026 requirements
EV charger sourcing Europe 2026
TEN-T charging corridor power thresholds
AFIR’s 2026 milestones mean distributors need to source higher-power DC chargers with standardized connectors and verified grid-load compatibility now, not after national permitting rules catch up, because production and certification lead times for compliant hardware already eat into the window before the deadline. If your sourcing roadmap still treats 2026 as a far-off planning horizon, you’re behind. The hardware decisions that satisfy AFIR’s power thresholds and connector requirements need to be locked in months before a station goes live, and that clock is already running.
Key takeaways
AFIR targets a charging station every 60 km along main EU routes by 2026, with power thresholds per site stepping up through 2028, so corridor hardware needs to be specced toward the top of the power pool now.
AFIR sets EU-wide minimums, but grid connection approval and permitting remain national matters, so multi-country rollouts need separate compliance timelines per market rather than one blanket deadline.
CE and UL certification cycles plus site permitting mean specs and orders need to be finalized well before a regulatory milestone, not at it, since production lead times eat into the compliance window.
Always verify power thresholds and spacing figures against the official AFIR text (Regulation (EU) 2023/1804) or national guidance before quoting a project, since figures get refined after the initial regulation.
What AFIR Actually Requires on TEN-T Corridors by 2026
Strip away the legal language and AFIR comes down to two numbers distributors actually need: spacing and power. By 2026, electric vehicles should be able to find a charging station every 60 km along the main EU routes, a target built around the TEN-T core road network. That spacing requirement is what drives site selection for highway operators and the distributors bidding to supply them.
Power thresholds step up alongside spacing. 2026 and 2028 both function as milestone years where minimum power output per site increases, pushing corridor stations toward higher-kW DC pools rather than the lower-power units that served earlier deployment phases.
EU minimums, national execution
AFIR sets EU-wide minimums, but permitting, grid connection approval, and site allocation remain national responsibilities. A spacing or power figure that’s correct under the regulation doesn’t guarantee a smooth path to actually energizing a site in any given member state.
Treat any specific kW or km figure in this article, or any other, as a snapshot. EU AFIR (Alternative Fuels Infrastructure Regulation) mandates public charging deployment and supports infrastructure investment across all EU member states, but the regulation itself gets refined through delegated acts and national transposition notices. Check Regulation (EU) 2023/1804 directly, or your national ministry’s published guidance, before you finalize a bid.
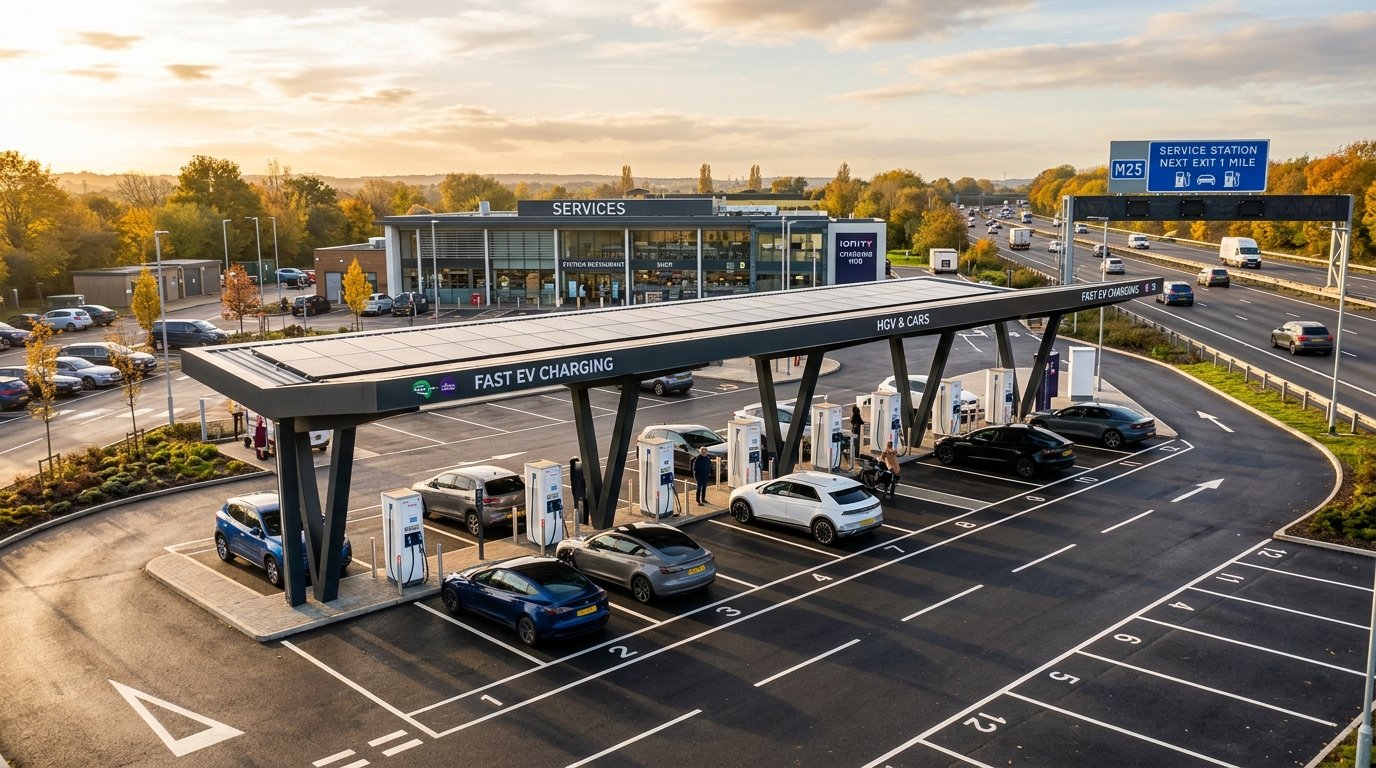
Highway service station with multiple DC fast charging bays spaced along a European corridor
Why the 2035 Combustion Engine Phase-Out Changes the Sourcing Math
The 2035 phase-out of new petrol and diesel car sales sets a distant horizon, but it also front-loads demand well before that deadline arrives. Distributors who wait for 2028’s thresholds to firm up before committing to a sourcing strategy are competing against everyone else for the same production slots at the same deadline. That’s a bad position to be in.
Fleet operators converting ahead of the ban are already pulling demand forward. Depot charging and highway charging for early-adopter fleets are live procurement categories right now, which is exactly why AFIR’s 2026 milestone matters more for near-term sourcing decisions than the 2035 phase-out itself. The phase-out sets direction; 2026 sets your actual delivery schedule.
Trucks and vans move first
CO2 targets for vans and trucks are tighter on a faster timeline than passenger car rules, which pushes logistics fleets toward electrification earlier than the broader passenger market. That shifts near-term demand toward higher-power DC infrastructure sooner than a passenger-only reading of AFIR would suggest. If you’re sourcing for a logistics hub or corridor site that serves mixed vehicle classes, size for the heavier end of that demand curve, not the average.
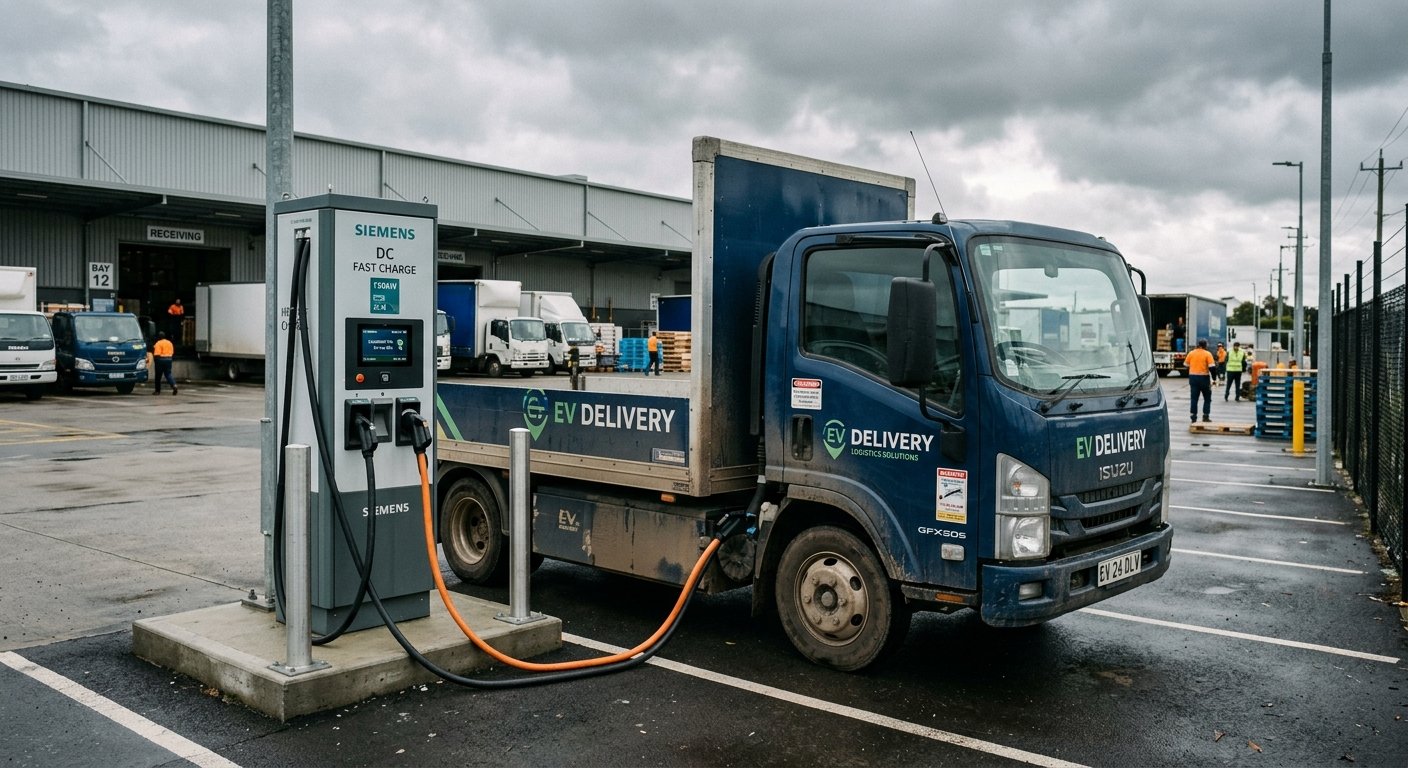
Electric delivery truck charging at a logistics depot with a high-power DC charger
Truck, Bus, and Hydrogen Mandates Distributors Overlook
Heavy-duty power pools are separate and higher. AFIR sets distinct, higher power thresholds for heavy-duty vehicle charging pools compared with passenger car corridors, which pushes distributor demand toward higher-kW DC product lines rather than general-purpose units.
Hydrogen infrastructure runs in parallel. Hydrogen refueling station requirements apply alongside electric charging mandates on the same corridors, meaning mixed-infrastructure sites are becoming standard at logistics hubs. If you’re bidding on a corridor site RFP, expect co-located fueling infrastructure requirements even if your scope is purely electric.
Bus depots follow their own design logic. Pantograph versus plug-in charging for bus depots is a separate engineering decision tree with its own duty-cycle considerations, covered in detail in our guide to matching DC chargers to duty cycles rather than repeated here.
What Power Output and Connector Specs Actually Satisfy AFIR by Site Type
Stop comparing hardware purely on kW rating and start matching power tier to site type, because AFIR doesn’t treat all sites the same.
Highway corridor sites
These need DC fast chargers scaled toward the top of the AFIR power pool. The regulation itself sets the bar: fast charging stations along the TEN-T core network must reach a minimum power output of 400kW by 2026, with the requirement scaling further by 2028. That figure comes from the regulation, not from a generic industry rule of thumb, and it’s what corridor-site specs should be measured against.
Urban hubs and retail
Dwell time and vehicle mix are different here. Take a hypothetical retail site with moderate daily traffic and shorter dwell times: it can often justify a lower DC power tier than a highway corridor site, without over-specifying hardware the location doesn’t need. AFIR’s power minimums apply specifically to corridor sites, so the right tier for an urban or retail location depends on actual vehicle mix and turnover rather than a fixed regulatory number.
Depot and fleet sites
These answer to AFIR indirectly, through grid connection and permitting rules rather than the spacing mandate. Spec decisions here should follow duty-cycle logic, which we cover in our fleet charging infrastructure guide, not corridor logic.
Connector standardization
CCS2 is the de facto standard under AFIR for passenger and light-commercial vehicles across the EU, separate from NACS or GB/T considerations relevant to other markets. See our breakdown of connector standards for 2026 for the cross-market picture.
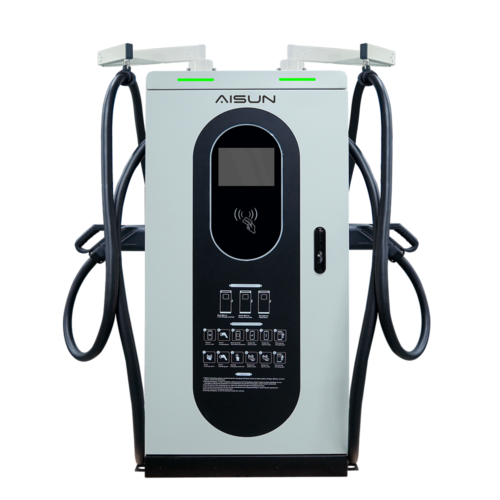
AiPower’s DC EV Charger European Standard line, including the 30kW power module configuration, illustrates how modular power scaling lets distributors match a single platform to different site tiers instead of stocking separate hardware families for each power class. The DC EV Charger spans a Power Range of 30KW to 480KW on 380V±15% three-phase input, which covers the full range from urban hub to corridor-grade deployment on one architecture.
Grid Load and Power Electronics: The Engineering Side Nobody Else Explains
Hitting AFIR’s 400kW minimum by 2026 isn’t a procurement checkbox, it’s a grid capacity problem first. A charging pool built to that threshold draws load comparable to a small industrial facility. Distributors quoting corridor projects need to ask about substation capacity before they specify hardware, not after.
Modular scaling beats over-provisioning
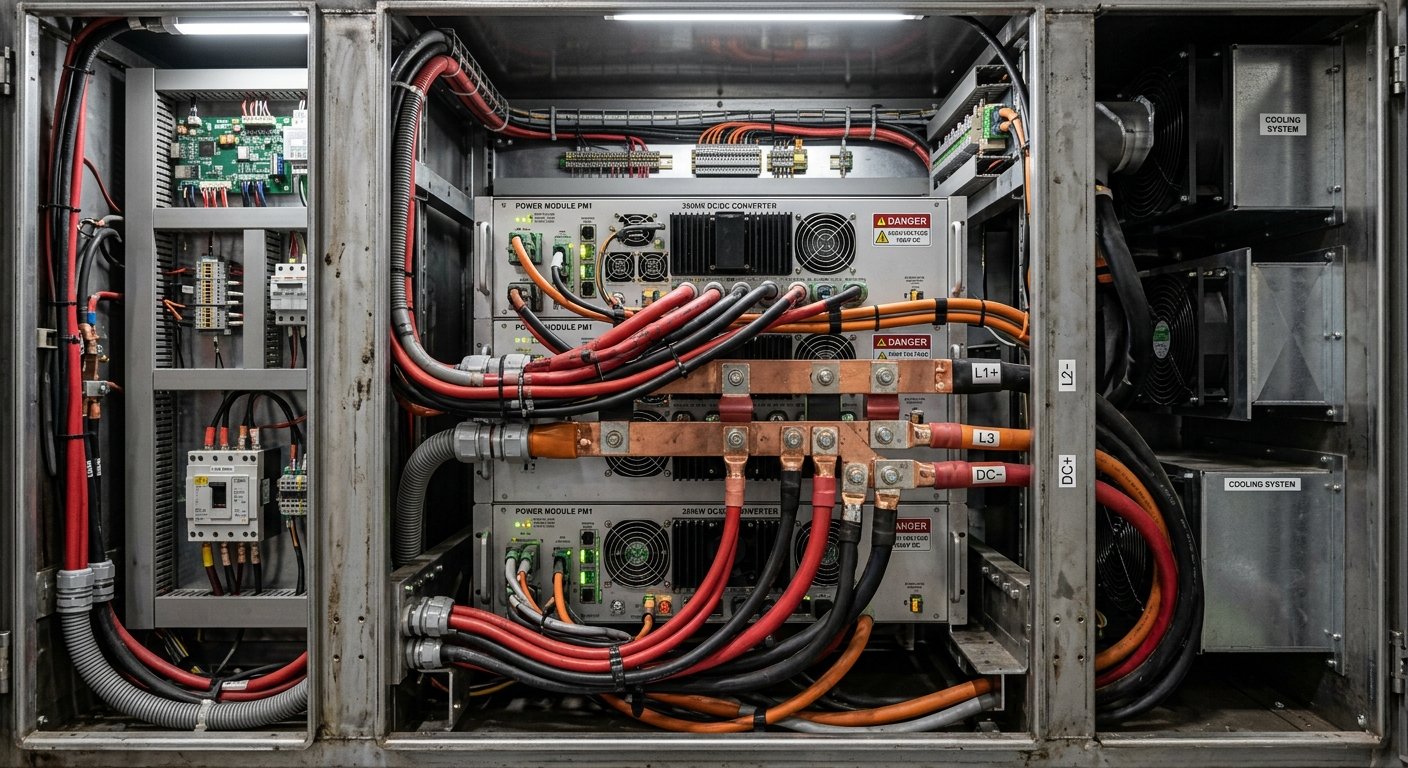
Modular power module architecture lets a site scale output over time, adding modules as the grid connection gets upgraded, instead of over-provisioning hardware on day one that the local grid can’t actually support yet.
Protection schemes matter more at high power density
AiPower’s DC EV Charger features 8-layer protections covering over-current, under-voltage, and related fault conditions. That depth matters more at high-power corridor sites, because fault conditions scale with power density: the higher the output a site runs, the faster a fault can propagate through the system if protection layers aren’t built in from the start.
Load balancing and dynamic power sharing across multiple stalls at one site is often the practical way to meet AFIR’s per-site power minimum without triggering a full grid upgrade immediately. We’ve covered the mechanics of this in our piece on comparing chargers beyond raw kW figures, which is worth reading alongside this one: why kW alone doesn’t tell you enough.
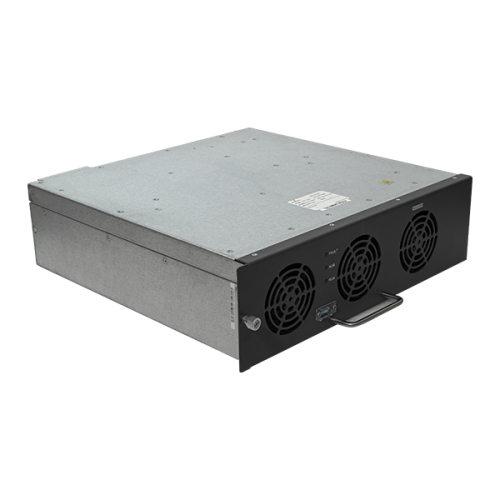
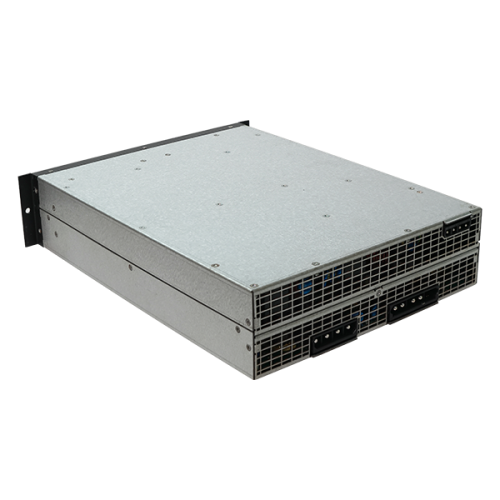
Internal power modules of a DC fast charger showing modular architecture and protection circuitry
Procurement Timelines: Aligning OEM/ODM Lead Times With 2026/2028 Deadlines
Certification and permitting eat far more of the calendar than most distributors budget for.
Finalize specs before the deadline, not at it. CE and UL certification cycles, plus local site permitting, mean distributors should be locking specs and placing orders well ahead of a regulatory milestone, not scrambling as it arrives.
Vet production capacity and certification status upfront. ODM partners with established production capacity can shorten the gap between spec decision and installed hardware. Ask about current production capacity and certification status before negotiations go deep, not mid-negotiation. AiPower’s solutions hold UL and CE certifications, which is the kind of baseline documentation to request from any supplier you’re evaluating.
Plan for staggered compliance across countries. National transposition of AFIR doesn’t move in lockstep across member states, so a multi-country rollout needs separate timelines per market rather than one blanket deadline.
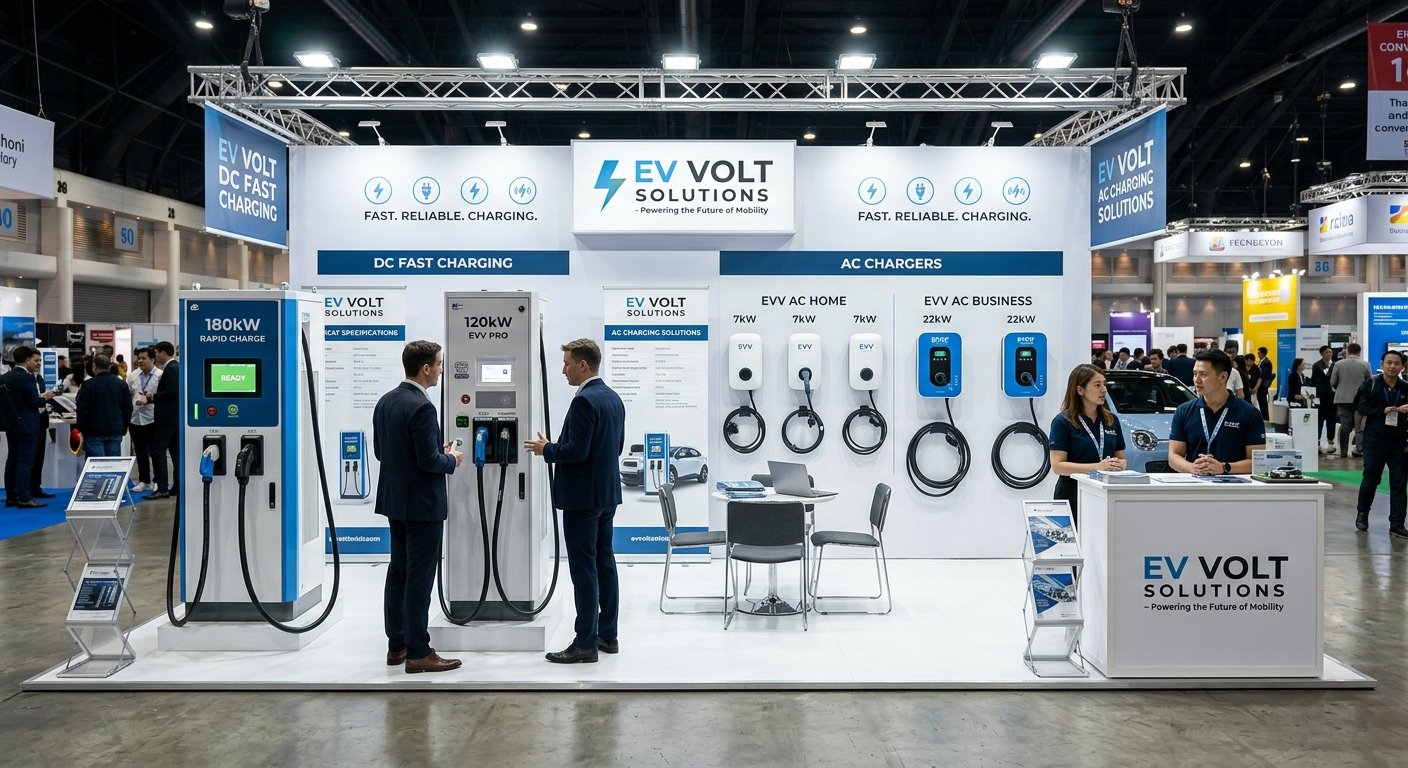
Check hardware readiness against trade show demonstrations. AiPower presented DC fast chargers, AC EV chargers, portable EV chargers, and forklift battery chargers at Power2Drive Europe 2025, held May 7 to 9 in Munich, Germany, and delivers tailored solutions to over 30 countries worldwide.
Trade show exhibition display of DC fast chargers and AC chargers for the European market
Why One EU Directive Still Means 27 Different Permitting Processes
AFIR is directly applicable, but execution isn’t. AFIR is a regulation and applies directly across the EU, but grid connection approval, land permitting, and incentive programs remain national or even municipal matters.
Track permitting separately from the EU deadline. Distributors operating across multiple EU countries should track country-specific incentive and permitting timelines separately from the EU-level AFIR deadline. Our region-by-region incentive tracking guide covers this in more depth without duplicating it here.
Build a split checklist. A practical move: separate “what AFIR requires” from “what the local grid operator or municipality requires” in your project checklist. Bidding on a corridor project in Germany versus Poland can mean very different lead times for the exact same charger spec, even though both fall under the same EU regulation.
How to Verify Current Figures Before You Quote a Project
Figures shift after the initial text. Power thresholds, spacing distances, and incentive figures tied to AFIR get refined through delegated acts and national guidance after the regulation’s initial publication, so a number correct a couple of years ago may have already moved.
Verify at the source, not from a blog. Before quoting power specs or compliance claims in an RFP response, check the current figure against the official EU AFIR text, Regulation (EU) 2023/1804, or the relevant national ministry publication. That includes this article: treat anything here as a starting point for verification, not a final citation.
Make verification a workflow step. Build this check into your RFP response process so sourcing decisions don’t get locked to an outdated figure simply because it was convenient to cite.
What Distributors Should Do Before the Next Milestone Hits
The decision sequence is straightforward even if the regulation isn’t: confirm the site type and power tier you actually need, check grid capacity realistically before committing to a spec, verify current regulatory figures at the official source, then lock in a supplier with the certification and production capacity to match your timeline. Skip any one of those steps and you’re sourcing against a moving target.
Modular DC platforms that scale from lower kW configurations up toward the 480kW range give distributors flexibility to meet different AFIR site tiers without redesigning a sourcing strategy for every individual project. That’s the practical advantage of a single product family over stocking separate hardware lines for each power class.
If you’re evaluating specs against AFIR site requirements, AiPower’s AC EV Charger European Standard, with a power range of 7kW, 11kW, and 22kW, and the DC EV Charger European Standard, scaling from 30kW to 480kW, are a reasonable starting point for that comparison. No one can promise the regulatory figures won’t shift again, but a modular, certified hardware base gives you room to adjust without starting the sourcing process over.
Frequently asked questions
What does AFIR require for EV charging stations by 2026?
AFIR targets a charging station roughly every 60 km along main EU TEN-T routes by 2026, alongside minimum power output thresholds per site that step up through 2028. These are EU-wide minimums; actual permitting and grid connection approval still depend on national rules, so always verify current figures against the official regulation text before finalizing a bid.
Is CCS2 mandatory for EV chargers under AFIR?
CCS2 functions as the de facto standard under AFIR for passenger and light-commercial vehicle charging across the EU, supporting cross-border roaming compatibility. Other connector types like NACS or GB/T remain relevant for different markets outside the EU regulatory scope, but EU corridor deployments should default to CCS2 compliance.
Subscribe the newsletter to get updated to news and promotions
Cookies give you a personalized experience,Сookie files help us to enhance your experience using our website, simplify navigation, keep our website safe and assist in our marketing efforts. By clicking "Accept", you agree to the storing of cookies on your device for these purposes. Click "Adjust" to adjust your cookie preferences.For more information, review our Cookie Policy