EV Charger Insurance and Liability: What Distributors Overlook Until a Claim Hits
Home / Blog / Guidelines / EV Charger Insurance and Liability: What Distributors Overlook Until a Claim Hits
08 Oct, 2026
charger warranty vs insurance
distributor liability EV charger
EV charger product liability
EV charging station claims
Insurance and liability exposure for EV chargers rarely gets scrutinized until something burns, fails, or injures someone — and by then, distributors often discover their coverage doesn’t apply the way they assumed. The core issue: most distribution agreements separate ‘product warranty’ from ‘liability coverage’ as if they’re the same thing, when insurers and courts treat them very differently. If you’re distributing chargers without a documented chain of liability from OEM to installer to site owner, you’re the default target when a claim gets filed.
Warranty and Liability Are Not the Same Contract
Here’s the mistake that costs distributors the most: assuming a manufacturer’s warranty doubles as liability protection. It doesn’t. A warranty says “we’ll fix or replace this if it fails.” Liability coverage says “we’ll pay if this failure hurt someone or damaged property.” Those are entirely separate financial exposures, and most OEM warranty documents explicitly exclude the second category.
This distinction matters most after the sale is done. If a charger you distributed causes a garage fire eighteen months post-installation, the warranty clause is irrelevant — the question becomes who carries product liability insurance, and whether it names you as an insured party or leaves you exposed as the importer of record. Distributors sourcing through OEM vs. ODM arrangements need to check this before signing, not after a claim arrives.
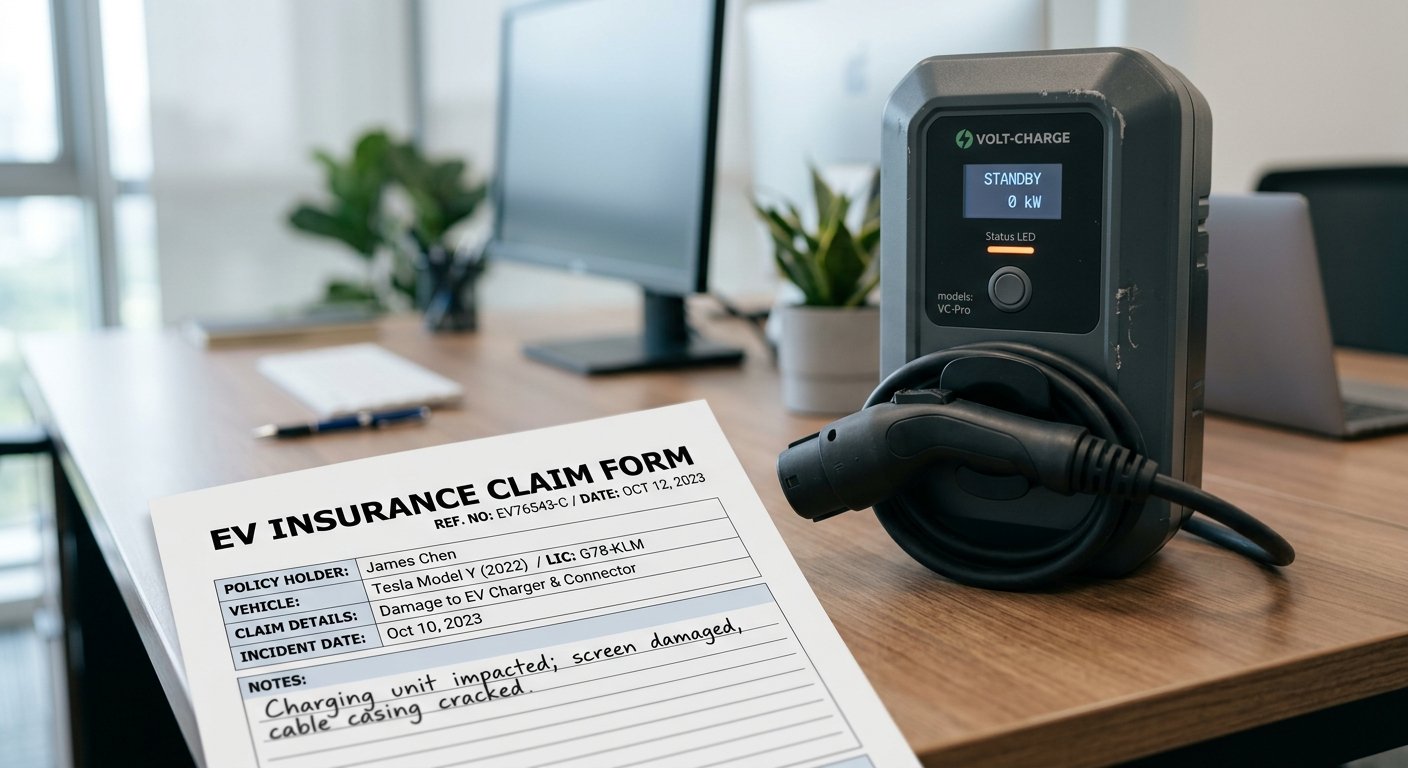
Insurance claim document beside an EV charger unit on a desk
The First Warranty Claim Reveals the Real Cost Structure
Nothing exposes weak liability planning faster than a first warranty claim. Distributors who source cheap units often discover, as detailed in our analysis of hidden warranty costs, that the manufacturer’s liability language quietly caps their exposure at the unit’s purchase price — not the actual damages incurred by the end customer.
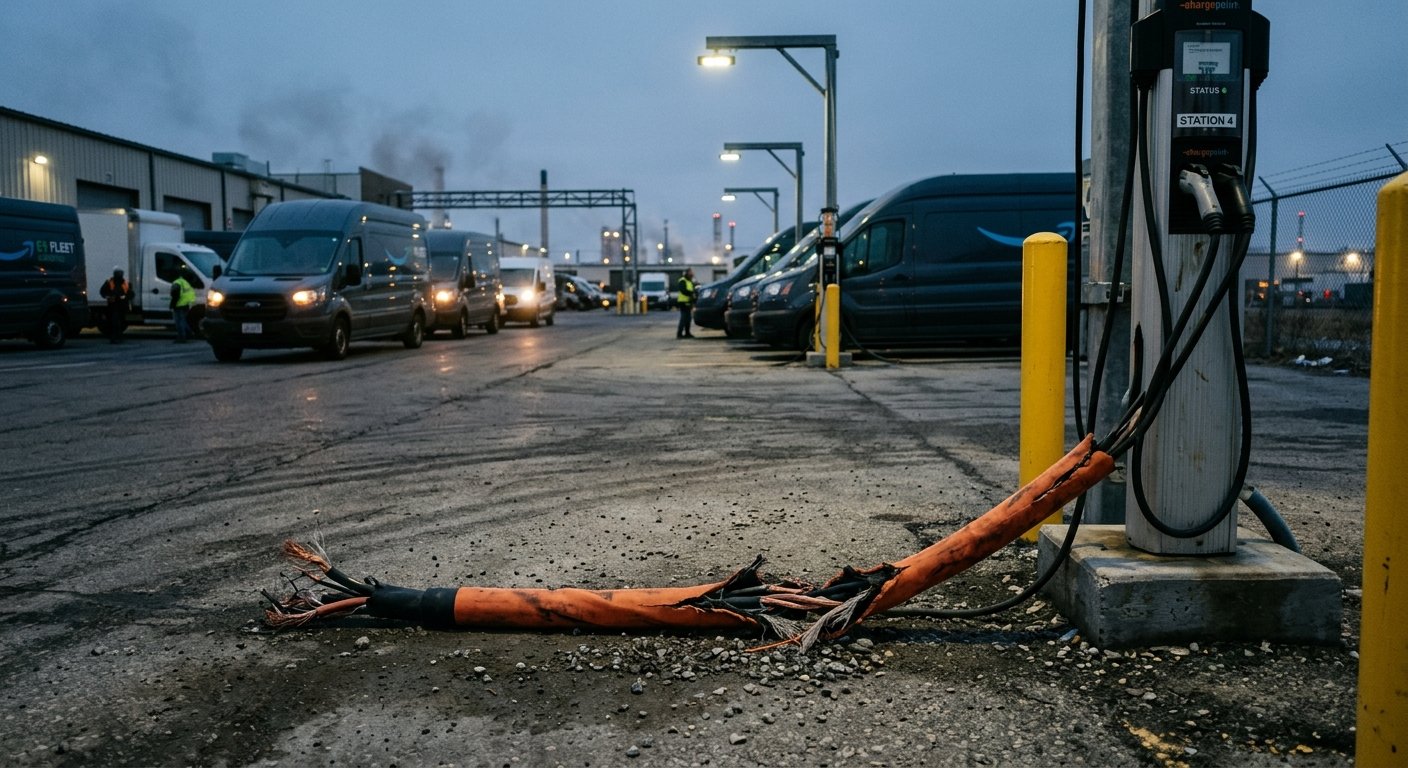
For instance, a fleet operator running a 50-vehicle overnight depot filed a claim after a charger’s ground fault detection failed and damaged three vehicle onboard chargers. The unit itself cost $4,200. The vehicle repair bill hit $38,000. The OEM’s contract capped their liability at unit replacement cost only — leaving the distributor negotiating the difference directly with the fleet operator’s insurer.
Damaged EV charging cable at a fleet charging depot
Certification Gaps Are a Liability Trigger, Not Just a Compliance Issue
Insurers ask one question before paying out a claim: was the product certified for the environment it failed in? If a charger passed UL or IEC testing for indoor use but was installed outdoors without the correct enclosure rating, that’s grounds for the insurer to deny the claim entirely — and push liability back onto whoever specified the unit.
This is why understanding IP ratings and outdoor lifespan limitations isn’t just an engineering nicety. It’s a legal defense. Distributors who can produce documentation showing the correct certification was matched to the deployment environment walk into a claim dispute in a completely different position than those who can’t.
Products that fail certification testing and get quietly redesigned without re-certification are a specific red flag insurers now look for during subrogation investigations.
Who’s Actually Named on the Policy?
Most distributors never ask to see the actual certificate of insurance from their OEM or ODM partner — they take “we’re covered” at face value. That’s a mistake. A certificate of insurance should name the distributor as an additional insured, not just list the manufacturer as the sole policyholder.
Without that additional-insured status, if a claim is filed against the distributor directly — which happens often, since the distributor is usually the party with the closest commercial relationship to the installer or site owner — the manufacturer’s policy may not extend any defense costs at all. You end up funding your own legal defense while the manufacturer’s insurer stays uninvolved.
What to Request Before Signing
A current certificate of insurance with policy limits, not just a policy number
Written confirmation of additional-insured status for the distributor
Product liability limits of at least $2M per occurrence for DC fast charger lines
Confirmation the policy covers international shipments, not just domestic sales
Business professionals reviewing an insurance and liability contract for EV chargers
Installation Errors Blur the Liability Line
A surprising number of claims trace back not to the charger itself but to the installation — yet distributors still end up named in the lawsuit because they recommended the installer or sold the unit as part of a bundled package. Ground fault wiring mistakes are a classic example; our breakdown of wiring mistakes behind ground fault errors shows how often these originate at the panel, not the charger.
If you’re bundling installation services — common in forklift charger installation and warehouse retrofits — get the installer’s general liability certificate on file for every project, not just the ones that seem risky. Claims almost never come from the projects you worried about.
Networked Chargers Add a Cybersecurity Liability Layer
Liability exposure isn’t limited to physical failure anymore. A networked charger that gets compromised and used to manipulate load balancing or trigger a grid disturbance can trigger a completely different category of claim — one most standard product liability policies weren’t written to anticipate.
Distributors deploying OCPP-connected fleets should review our cybersecurity checklist for networked chargers alongside their insurance broker, specifically asking whether the policy covers cyber-triggered equipment damage versus only data breach liability. These are usually written as separate riders, and most distributors have neither.
Contract Clauses Distributors Consistently Skip
Two clauses get overlooked far more often than they should: indemnification scope and defense cost allocation. Indemnification scope determines whether the OEM covers you for claims arising from their defect, or only claims arising from your own negligence — a huge difference. Defense cost allocation determines who pays the lawyers while liability is still being sorted out, which can take 12–18 months.
This connects directly to the warranty negotiation leverage discussed in why distributors lose deals over warranty terms — insurance and liability clauses should be negotiated in the same conversation, not treated as boilerplate legal text nobody reads until it matters.
Building a Claim-Ready Documentation Trail
When a claim does hit, the distributors who resolve it fastest are the ones with a paper trail — not the ones with the best legal team. That means keeping installation records, firmware update logs, certification documents, and correspondence with the OEM organized per project, per site, from day one.
This isn’t paranoia; it’s standard practice for anyone specifying equipment through a formal RFP procurement process. Fleet and site operators increasingly require this documentation upfront, before a claim is even a possibility, because their own insurers demand it as a condition of coverage.
Organized documentation binder for EV charger certification and installation records
Subscribe the newsletter to get updated to news and promotions
Cookies give you a personalized experience,Сookie files help us to enhance your experience using our website, simplify navigation, keep our website safe and assist in our marketing efforts. By clicking "Accept", you agree to the storing of cookies on your device for these purposes. Click "Adjust" to adjust your cookie preferences.For more information, review our Cookie Policy